Key takeaways
- An HMO is let room by room to several unrelated tenants; a buy to let is let as a whole to one household.
- HMOs usually bring in more rent from the same property, but mean more compliance, more furnishing and more management.
- Furnishing an HMO starts from £679 + VAT per room; a furnished buy to let starts from £2,399 + VAT for a one-bed.
- Neither is better in every case – it depends on your property, your area, your budget and how hands-on you want to be.
What's the difference?
A buy to let is a property let as a whole to one household – a single tenant, a couple or a family – on one tenancy. A house in multiple occupation (HMO) is a property shared by people who aren't from the same household, who share facilities such as the kitchen or bathroom. Each tenant typically rents a bedroom, and the landlord provides the shared spaces.
Councils decide whether a property needs an HMO licence, and the rules differ by area, so always check with your local authority before you buy or convert.
At a glance
| HMO | Buy to let | |
|---|---|---|
| Who lives there | Several unrelated tenants, each with their own room | One household |
| Rental income | Several rents from one property – often higher overall | One rent, usually more predictable |
| Voids | One empty room loses part of the income, not all of it | An empty property earns nothing |
| Compliance | Licensing, stricter fire safety and room-size standards | Standard landlord safety duties |
| Furnishing | Every bedroom plus shared living, dining and kitchen | Furnished or unfurnished – a smaller job |
| Management | More tenants, more turnover, more wear | Usually fewer changeovers |
The comparison shows the pattern, not exact figures – actual yields depend on your area, purchase price and costs, so run the numbers for each property and speak to your accountant and mortgage broker.
Income and risk
The main attraction of an HMO is spreading the rent across several tenants. If one room is empty, the others are still paying. A buy to let is simpler – one tenant, one rent – but an empty month means no income at all.
Set against that, an HMO has higher running costs and more things that can go wrong: more bedrooms to furnish, more wear, more tenant changes and often more bills to manage. See our guide on how to reduce void periods for what helps either type of property.
Compliance and paperwork
This is where the two differ most. Buy to let landlords still have to meet safety duties such as gas, electrical and smoke alarm checks. HMOs add further requirements, which can include a licence, stricter fire precautions and minimum room sizes – and conditions vary between councils.
- Room sizes – licensed HMO bedrooms in England must be at least 6.51m² for one adult. See our HMO furniture requirements guide.
- Fire safety – furniture in either type of let must meet the furniture fire safety regulations.
- Planning and mortgages – converting a house to an HMO may need planning permission in some areas, and not every lender offers HMO mortgages. Check both before you commit.
Furnishing costs compared
Here's what furnishing each type costs with our packages. All prices are + VAT, delivered, assembled and installed:
| Type | What you furnish | Prices from |
|---|---|---|
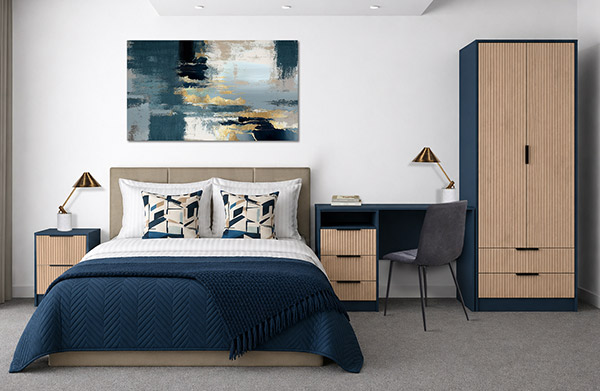
| HMO | Each bedroom with double bed, mattress, headboard, wardrobe and bedside | £679 per room |
| BTL 1 bed | Bedroom, living and dining in one package | £2,399 |
| BTL 2 bed | Two bedrooms, living and dining | £2,999 |
As an example, a five-bedroom HMO at the starting room price would be 5 × £679 = £3,395 + VAT for the bedrooms alone, before the shared living areas and kitchen. A two-bed buy to let package is £2,999 + VAT for the entire property. HMOs cost more to furnish – but they also bring in rent from several tenants. For a full breakdown, see how much it costs to furnish an HMO.
Which should you choose?
An HMO may suit you if you want to maximise income from one property, have a large enough house in an area with demand for rooms, and are comfortable with more management and compliance. A buy to let may suit you if you want a simpler, lower-maintenance investment, with fewer tenants and fewer rules.
Many investors do both – and with either one, furnishing the property well helps it let faster. A BTL can be let furnished or unfurnished; an HMO is almost always furnished. We can quote for both, and spread the cost with lease finance or a 60-day payment plan, subject to status.
Frequently asked questions
What is the difference between an HMO and a buy to let?
A buy to let is let to one household on one tenancy. An HMO is shared by unrelated tenants, usually each renting a room, with shared facilities such as a kitchen or bathroom.
Is an HMO more profitable than a buy to let?
An HMO can bring in more rent from the same property, but it also costs more to furnish, run and keep compliant. Work out the figures for your own property and area, and check with your accountant.
Is it more expensive to furnish an HMO than a buy to let?
Usually. HMO rooms start from £679 + VAT each, plus shared areas, while a furnished buy to let package starts from £2,399 + VAT for a one-bed and £2,999 + VAT for a two-bed.
Do I need a licence for an HMO?
It depends on the property and your council. Larger HMOs usually need a licence, and some councils require one for smaller shared houses too. Check with your local authority before you let.